
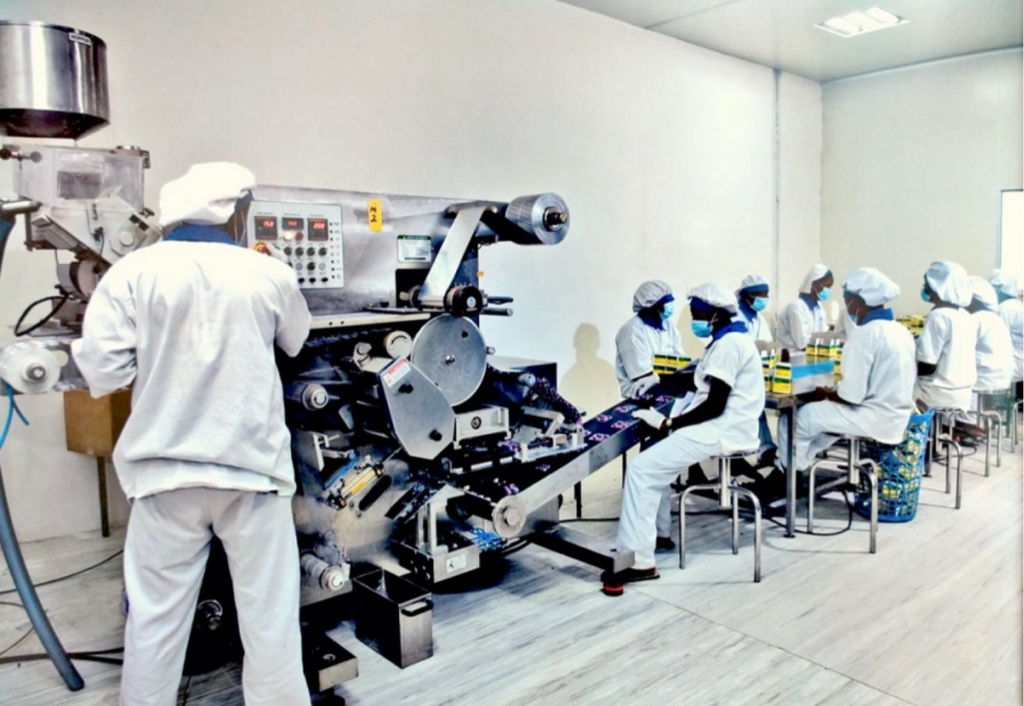
MeCure Industries Plc has opened an offer of up to N14 billion Series 8 Commercial Paper under its N40 billion Commercial Paper Programme.
The Lagos-based manufacturer of medicines and multivitamins has been using the market to raise money for its short-term working capital needs.
This offer carries an implied annual yield of 21%. Investors holding the paper for its full 267-day duration would earn approximately 15.36% on the amount invested, before applicable deductions, provided MeCure repays in full.
The offer opened on Wednesday, October 14, 2026, and closes on Tuesday, October 20, 2026.
What the offer circular is saying
- Issuer: MeCure Industries Plc.
- Programme size: N40 billion.
- Series: 8 — target size: Up to N14 billion.
- Tenor: 267 days.
- Discount rate: 18.2036% per annum.
- Gross implied yield: 21% per annum, stated as inclusive of withholding tax.
- Allotment date: Tuesday, October 20, 2026.
- Settlement date: Wednesday, October 21, 2026.
- Maturity date: Thursday, July 15, 2027.
- Minimum subscription: N5 million and multiples of N1,000 thereafter.
- Issuer ratings stated in the offer: A1 from DataPro and A3 from GCR.
- Listing: Nigerian Exchange Limited and/or FMDQ Securities Exchange Limited.
The offer:
The issuance follows MeCure’s offer of up to N10 billion Series 7 commercial paper in February 2026, which carried a 269-day tenor and a gross annualised yield of 21.75%.
- The latest offer increases the fundraising target by N4 billion, while offering a yield 0.75 percentage points lower over a similar period.
- Proceeds will support working capital, providing funding for the company’s operations while it converts production and sales into customer receipts.
- Investors purchase the paper below its repayment value and receive that value at maturity.
On N5 million actually invested, the stated annualised yield would generate about N768,000 in gross income over 267 days, using a 365-day calculation basis.
Total proceeds would be approximately N5.768 million, before applicable deductions and subject to full repayment.
Investment case
MeCure’s 21% annual yield is higher than the 17.16% and 18.91% offered by six-month and one-year Treasury bills at the October 14 auction.
- Investors earn more for lending to the company, although MeCure’s paper runs for a different period of 267 days.
- The yield also stands above September’s 14.63% inflation rate, suggesting an opportunity to grow money faster than prices. The actual benefit will depend on taxes, fees and how inflation changes before repayment.
- The more important question is whether MeCure can repay.
MeCure’s announcement that it fully repaid its N3 billion bond in April 2026 offers some reassurance about its ability to honour debt obligations.
Its growing business provides further support. Revenue increased 20.4% to N44.85 billion in H1 2026, while lower marketing expenses helped operating profit rise faster, by 41% to N10.90 billion.
- MeCure’s expansion is increasing its funding needs. The company invested N16.69 billion in facilities and equipment during H1 2026, well above the N1.45 billion in cash generated from operations. Borrowing and existing cash helped fund the investment, leaving N2.07 billion in cash at June.
- Total borrowings increased 19.6% from December to N66.17 billion—about N3 borrowed for every N1 of shareholders’ funds.
- The growing debt burden adds to the importance of managing borrowing costs. Finance costs rose 54.9% to N5.93 billion, absorbing 54% of operating profit, compared with 49% a year earlier.
MeCure’s operating profit still covered these costs, but they took a larger share of its earnings despite the growth in the business.
The new facilities could help reverse that trend if they generate enough additional sales and cash to outpace the associated costs. For CP investors, repayment confidence will depend on those cash receipts and the funding available when the paper matures.
Investor takeaways
The offer provides a gross annualised yield of 21%, equivalent to approximately 15.36% over 267 days.
- Sales and operating profit are growing, supporting the company’s earnings base.
- Expansion could strengthen future production and sales, but requires funding before the full benefits materialise.
Investors should confirm net income after applicable deductions and plan around the July 2027 maturity.
Risk considerations
The principal considerations are rising financing costs, cash committed to expansion and the timing of customer receipts.
- Further borrowing could absorb part of the benefit from stronger operating earnings.
- Slower collections or delays in generating returns from new capacity could increase funding needs.
- Investors seeking to sell before maturity may receive a different return from the advertised yield.
Sustained cash generation and a clear repayment funding plan would provide additional reassurance alongside MeCure’s earnings growth and stated credit ratings.

0 comment(s)
Leave a Comment